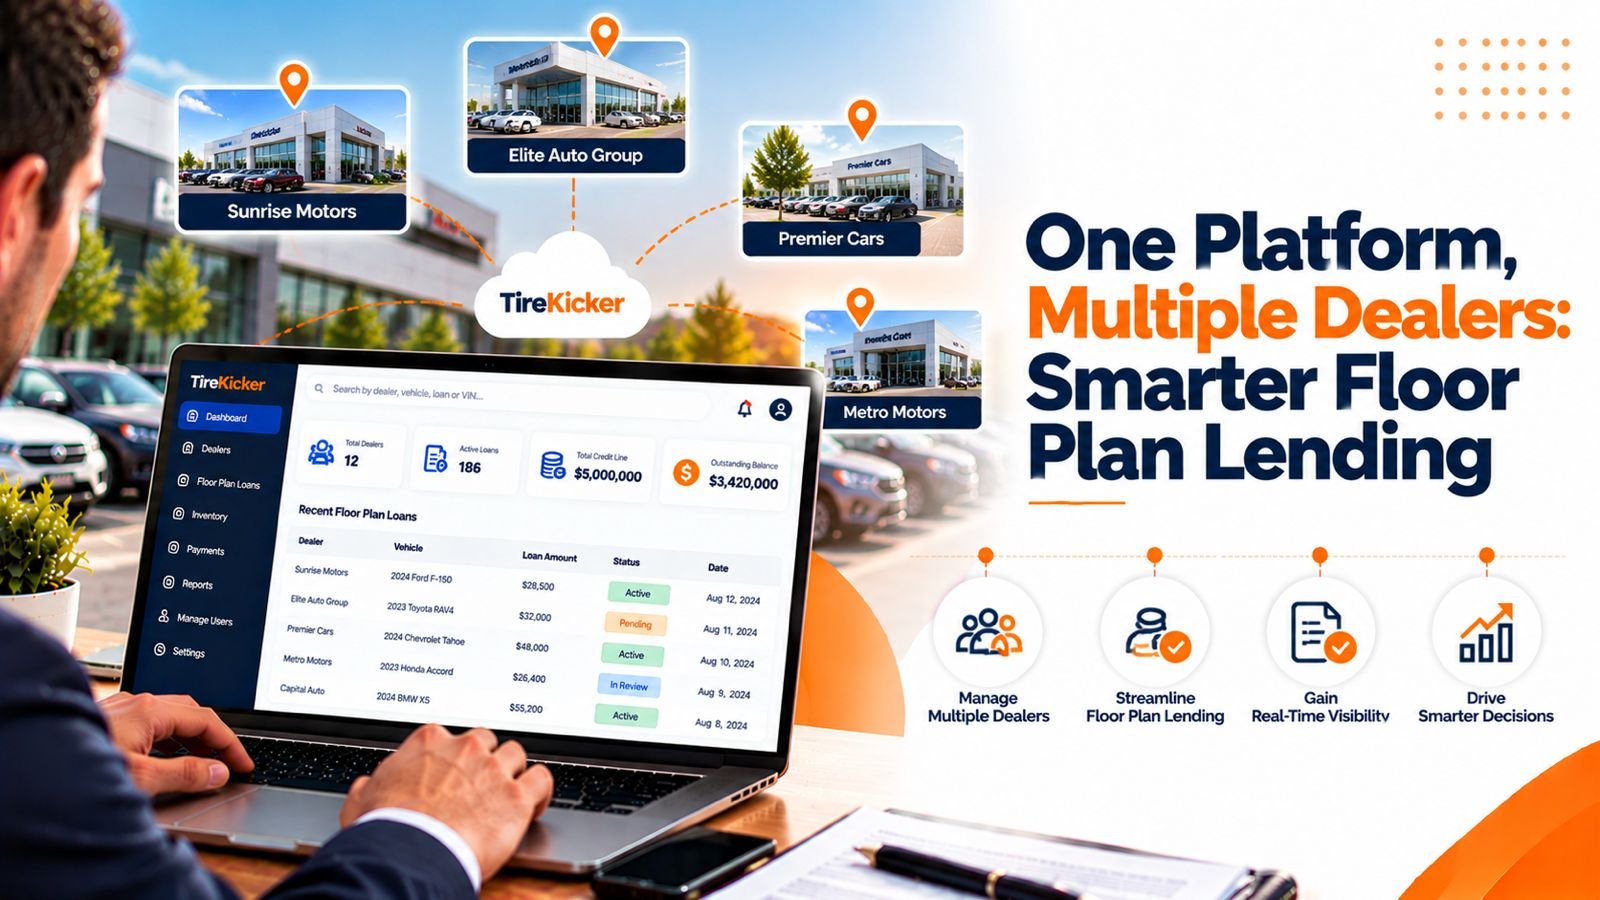
Managing multiple dealerships requires floor plan lenders to maintain accurate financing records, monitor vehicle inventory, track outstanding advances, coordinate audits, and oversee payments across dealer accounts. As a lending portfolio grows, keeping these activities organized becomes more challenging, particularly when teams rely on spreadsheets or disconnected systems.
The scale of the U.S. automotive market illustrates why organized dealer financing operations matter. According to the National Automobile Dealers Association’s 2025 full-year industry report, the United States had 16,990 franchised light-vehicle dealerships, which sold 16.2 million light-duty vehicles during the year. For lenders financing dealership inventory, maintaining accurate records and consistent oversight across dealer relationships is an important operational responsibility. Read the NADA 2025 industry report.
Floor plan lending software helps lenders bring dealer accounts, financed inventory, payment activity, and related workflows into a centralized system. Rather than managing each dealership through separate records, lenders can organize dealer-level information while maintaining visibility across their portfolios.
Unlike traditional business loans, floor plan lending ties financing to dealership inventory, which means lenders need accurate records connecting each financed vehicle to its dealer account and outstanding advance. Managing these relationships across multiple dealerships makes organized inventory and financing records especially important.
Why Managing Multiple Dealers Is Challenging for Floor Plan Lenders
Every dealership has its own financing records, inventory, outstanding advances, payment activity, and collateral documentation. As lenders add more dealers to their portfolios, they must manage these differences while maintaining consistent processes and accurate information.
Keeping Dealer Accounts and Financing Records Organized
Each dealer relationship generates information that lenders need to maintain, including account details, financing history, credit limits, advances, transactions, and supporting documentation.
When records are spread across spreadsheets, emails, and separate applications, employees may need to search several sources to answer routine account questions. Keeping information updated across these sources can also create inconsistencies and additional administrative work.
Lenders need a structured way to maintain individual dealer records without treating every account as a completely separate operation.
Monitoring Inventory and Outstanding Advances Across Dealerships
Floor plan lenders finance specific inventory assets, so understanding outstanding balances alone is not enough. They also need to know which vehicles secure those advances and how inventory changes affect their exposure.
When a lender finances several dealerships, tracking vehicles across different locations adds complexity. Staff must connect vehicle identification numbers (VINs), advances, inventory status, and outstanding balances to the appropriate dealer accounts.
Without organized records, reconciling financed inventory and investigating discrepancies can require considerable manual effort. A clear view of dealer-level inventory and financing activity helps lenders maintain better oversight.
Coordinating Payments, Audits, and Collateral Documentation
Managing multiple dealerships involves recurring responsibilities beyond approving advances. Lenders must track payments, review outstanding obligations, conduct inventory audits, and maintain title and collateral records.
These activities may involve different employees, deadlines, and documentation requirements. As the portfolio expands, coordinating them through manual processes can become increasingly difficult.
A missed follow-up or incomplete record may require additional investigation. Lenders therefore need consistent workflows that help them manage these responsibilities across their dealer networks.
Maintaining Consistent Oversight as the Portfolio Grows
Lenders must understand the position of individual dealerships while also monitoring their overall portfolios. They need to review account activity, identify outstanding obligations, and assess financing exposure without losing sight of dealer-specific requirements.
If every account follows a different process, comparing information and preparing reports can take longer. Standardized workflows and centralized records help lenders maintain consistency as their dealer relationships expand.
How Floor Plan Lending Software Helps Lenders Manage Multiple Dealers
Floor plan lending software helps lenders organize dealer accounts, monitor financed assets, manage financial activity, and maintain supporting records through a more connected workflow.
Centralize Dealer Accounts and Financing Information
A centralized system provides a common place to access dealer profiles, financing records, and related transactions. Instead of searching through separate files, employees can retrieve relevant information through a consistent process.
This can simplify account reviews, help staff investigate questions, and reduce the administrative effort involved in maintaining records across multiple dealerships.
Lenders evaluating auto dealer management software should look for capabilities designed for the financing side of dealership relationships, including dealer account management, credit limits, advances, inventory oversight, and portfolio reporting.
The objective is not simply to store information in one place. It is to organize the relationship between dealer accounts and the financing activities associated with them.
Track Financed Inventory and Advances by Dealer
Inventory tracking is central to floor plan lending because each financed vehicle represents an asset associated with an outstanding advance.
Specialized software helps lenders organize inventory records by dealership and locate individual vehicles using identifying details such as VINs. Depending on the platform, lenders can also review associated financing information, balances, curtailments, and inventory status.
This makes it easier to connect a specific vehicle with the correct dealer account and financing record. Staff can review inventory at the dealership level while maintaining a broader view of the assets financed across the portfolio.
For lenders managing many dealerships, this visibility helps organize collateral oversight and supports more consistent reconciliation of inventory and financing information.
Organize Dealer Billing and Payment Activity
Payment activity can become harder to manage as the number of dealer accounts increases. Lenders must maintain accurate transaction records, review outstanding obligations, and investigate discrepancies when account information does not match.
Floor plan lending software can connect billing and payment records with dealer accounts and financing activity. This helps staff review transactions in context rather than piecing together information from separate systems.
Depending on the platform’s capabilities, lenders may also be able to manage statements, payment tracking, and collections workflows through the same environment.
Centralized records do not eliminate the need for financial reviews, but they can provide a more organized foundation for handling recurring payment responsibilities across multiple dealerships.
Coordinate Inventory Audits Across Multiple Locations
Inventory audits help lenders verify that financed vehicles can be accounted for and that recorded collateral information reflects the dealer’s actual inventory.
When a lender works with several dealerships, audit coordination requires an organized approach to scheduling, recording findings, identifying discrepancies, and tracking follow-up activities.
Floor plan lending software with audit management capabilities can help staff maintain audit records and associate findings with the relevant dealer accounts. This gives lending teams a more consistent way to review audit activity across their portfolios.
The software supports the process, while lender personnel remain responsible for carrying out appropriate verification procedures and resolving exceptions.
Monitor Titles and Collateral Documentation
Vehicle titles and related collateral records are important to lenders because they support the management of financed assets and associated documentation requirements.
When records are stored in different locations, employees may need to spend additional time locating documents, confirming their status, or checking which vehicle a record belongs to.
Dedicated title and collateral management capabilities help organize this information alongside dealer and inventory records. Depending on the platform, lenders may also be able to track title status and manage release workflows.
Keeping collateral information organized makes it easier for authorized staff to review records and follow established procedures across multiple dealer accounts.
Use Dealer-Level Reporting to Support Portfolio Decisions
Lenders need to understand both individual dealer performance and their overall portfolio position. Dealer-level reports can help staff review account activity, while portfolio-level summaries provide a broader view of outstanding financing and inventory.
Centralized reporting can reduce the effort required to compile information from separate files and help teams review data using consistent formats.
Useful reporting capabilities may include outstanding advances, credit utilization, payment activity, inventory summaries, and audit status. The specific reports available depend on the software platform.
For lenders managing a growing dealer network, organized reporting helps make relevant information easier to review and supports more informed portfolio oversight.
What to Look for in Floor Plan Lending Software for Multi-Dealer Management
Not every loan management platform is designed around the operational requirements of floor plan financing. When evaluating software, lenders should consider whether it supports the relationship between dealer accounts, individual advances, financed vehicles, payments, audits, and collateral.
Key capabilities to evaluate include:
- Centralized dealer management: Maintain dealer profiles, financing records, and account information through consistent workflows.
- Inventory and advance tracking: Connect financed vehicles with the appropriate dealer and advance records.
- Financial activity management: Organize billing, payments, balances, and relevant account transactions.
- Audit and collateral oversight: Maintain audit records and organize title and collateral information.
- Portfolio reporting: Review dealer-level activity and broader financing exposure using consistent reports.
- Access controls: Manage user permissions so employees can access the information appropriate to their roles.
- Scalability: Determine whether the platform can accommodate additional dealerships without introducing unnecessary operational complexity.
Lenders should also evaluate how well the software fits their existing processes, reporting requirements, and internal controls. The goal is to choose a system that supports the actual demands of dealer financing rather than one that requires extensive workarounds.
When evaluating floor plan lending software, lenders should assess whether the system connects dealer accounts, financed inventory, advances, payments, and collateral records. Keeping these related records accessible within a consistent workflow can make it easier to manage individual dealerships without losing sight of the wider portfolio.
Managing Multiple Dealers with TireKicker 2.0
TireKicker 2.0 is a cloud-based floor plan lending software solution designed for automotive lenders, community banks, credit unions, and finance companies that finance dealership inventory.
Its capabilities address several of the operational requirements involved in managing multiple dealer relationships.
Loan and inventory management helps lenders organize advances and associated vehicles, with inventory visibility by dealer, VIN, or asset type. Billing and payment processing supports financial workflows, while audit and compliance functionality helps organize inventory verification activities. Title and collateral management supports the handling of documentation associated with financed assets.
TireKicker 2.0 also offers reporting and analytics capabilities to help lenders review dealer and portfolio information. User management features support access controls for different roles.
These capabilities bring key lending activities into a platform designed around floor plan financing. For lenders managing multiple dealerships, this can provide a more structured way to organize dealer accounts, inventory, financial transactions, and collateral records.
When dealer information is scattered across spreadsheets and disconnected applications, employees may need to enter the same information repeatedly, reconcile records manually, and search multiple systems to review account activity. Connecting relevant information through centralized workflows can help lenders reduce manual loan processing and spend less time on repetitive administrative tasks.
The right software should complement established lending controls rather than replace them. Lenders remain responsible for credit decisions, collateral verification, account reviews, and appropriate risk management procedures.
Conclusion
Managing multiple dealerships requires floor plan lenders to coordinate dealer accounts, financed inventory, outstanding advances, payments, audits, and collateral documentation. As portfolios grow, disconnected records and inconsistent workflows can make these responsibilities harder to manage.
Floor plan lending software helps organize these activities through centralized dealer information, inventory tracking, financial workflows, audit records, and reporting. By keeping relevant information connected, lenders can make routine account reviews more manageable and maintain visibility across their dealer portfolios.
Choosing a platform built specifically for floor plan lending is important because the work extends beyond general loan administration. Lenders need to understand the relationship between each dealership, its financed vehicles, and the advances associated with those assets.
TireKicker 2.0 brings key floor plan lending workflows together, helping lenders manage dealer accounts, track financed inventory, and keep financing records organized. These capabilities support a more consistent approach to overseeing multiple dealerships and maintaining visibility across the lending portfolio.


